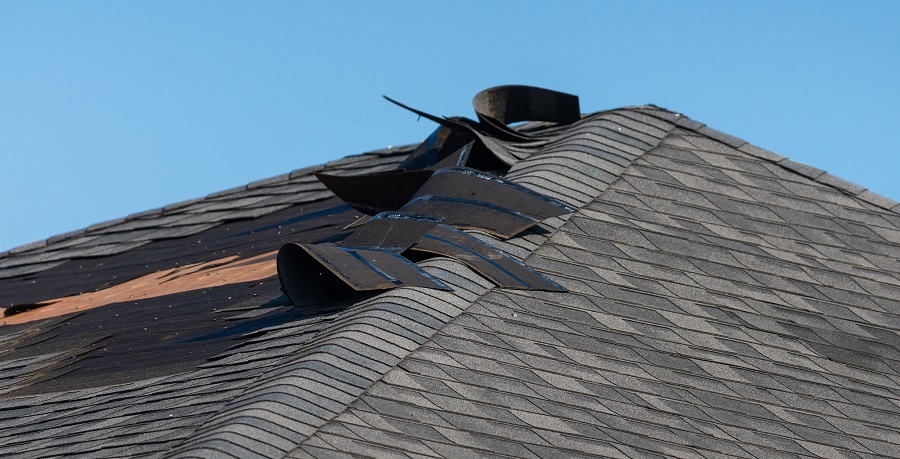
After hail or wind hits a roof, the damage is only half of the problem. The other half arrives as paperwork: an inspection report, an estimate, a claim letter and a scope of loss. Each was written by someone with a different job, and none is meant to duplicate another. Reading them side by side lets a homeowner spot a gap early, while it is still a question and not a dispute.
Southwest Missouri makes the exercise worthwhile. The April 28, 2026 hailstorm brought stones from roughly baseball size to as large as 4.75 inches across the Springfield area, with home damage that included roofing, siding, gutters and windows. A storm like that rarely harms only shingles. A document that prices only the roof surface can leave out parts with the same hailstones struck, so every line deserves a read.
Start with the roofer’s side. An inspection report records observations: where damage was found, on which slopes, and how it was photographed. An estimate turns those observations into a proposed repair or replacement with materials, labor and quantities. Neither one decides coverage. That belongs to the insurer, whose claim letter states the decision and points to policy language, and whose scope of loss lists the items, quantities and amounts it counted. Policy terms shape the outcome too, including whether roof coverage pays full replacement cost or a depreciated actual cash value. That page of the policy is worth finding before any estimate is compared to any scope.
Homeowners in Springfield and across Southwest Missouri who want help lining these documents up can turn to Trinity Roofing, a locally owned company that handles Insurance Claims and Storm Damage Repair alongside roof repair and roof replacement. Owner Matthew brings more than 15 years of roofing experience in the area and works alongside the insurance adjuster so storm damage is properly documented and homeowners have the information they need to decide. If you would like a second set of eyes on your own roof, request a roof inspection and written estimate.
The documents at a glance
| Document | What it contains | What to check |
|---|---|---|
| Roofer’s inspection report | Findings by slope or component, photos, notes on the type and location of damage | Whether photos match the written findings, whether every slope is covered, and whether wind and hail marks are described separately |
| Repair or replacement estimate | Line items for materials, labor, tear off, disposal and flashing, with quantities and a total | Measurements, product names, and whether each line states a quantity instead of a lump sum |
| Insurer’s claim letter | The decision, the policy provisions cited, the deductible and any depreciation withheld | Which coverage terms apply, which deductible was used, and what the letter says about further review |
| Scope of loss | The insurer’s own itemized list with quantities and unit amounts | Whether each damaged component appears, and how the quantities compare with the roofer’s measurements |
Where the two documents diverge
A roofer’s estimate prices the work needed to complete a proper repair. An insurer’s scope prices what the insurer determined the policy covers, after applying its terms. The Missouri Department of Commerce and Insurance explains in its roof coverage guidance that some policies pay only a depreciated actual cash value for a roof, and it recommends checking the declarations page to see which applies. That alone can separate two totals that describe the same roof.
Other differences come from different measurements, a different count of damaged slopes, or a component one document includes and the other leaves out. Some differences reflect honest disagreement about the damage and others reflect a simple omission. Identifying which one applies is the point of reading both.
What a vague line can signal
Watch for phrases such as “repair as needed,” “miscellaneous,” or a single allowance with no quantity. These lines leave the work undefined, which can lead to revised numbers later. Missing product details matter as well. An estimate that never names the shingle type, the number of layers being removed, or the underlayment leaves a homeowner unable to tell what is being bought. The same caution applies to insurer scopes, where a line without a quantity is hard to check against the roof.
What a missing line can signal
Absence is harder to see than vagueness, so read with a short list of questions. Does the document address tear off and disposal? Are flashing, drip edge, vents and ridge components mentioned? Are gutters, siding and window screens included when the storm report suggests they were struck? A missing line might mean the item was undamaged, or it might mean nobody looked. Asking which is true costs nothing.
Matching the storm to the paperwork
Public weather records give the paperwork some context. The National Weather Service’s review of the April 28, 2026 hailstorm documents the hail sizes and the kinds of home damage reported across the Springfield area. Keeping a record like that beside your reports and letters helps when asking whether a component belongs in a scope.
Keeping the conversation useful
When two documents disagree, write down the specific lines in question and ask each party to explain them in writing, with photos or measurements where possible. Questions about how a policy applies belong with the insurer, the agent, or the Missouri Department of Commerce and Insurance, which takes consumer questions about claims. Keep copies of every report, letter and photo in one folder. A clear paper trail makes each later conversation shorter, whatever the final scope looks like.